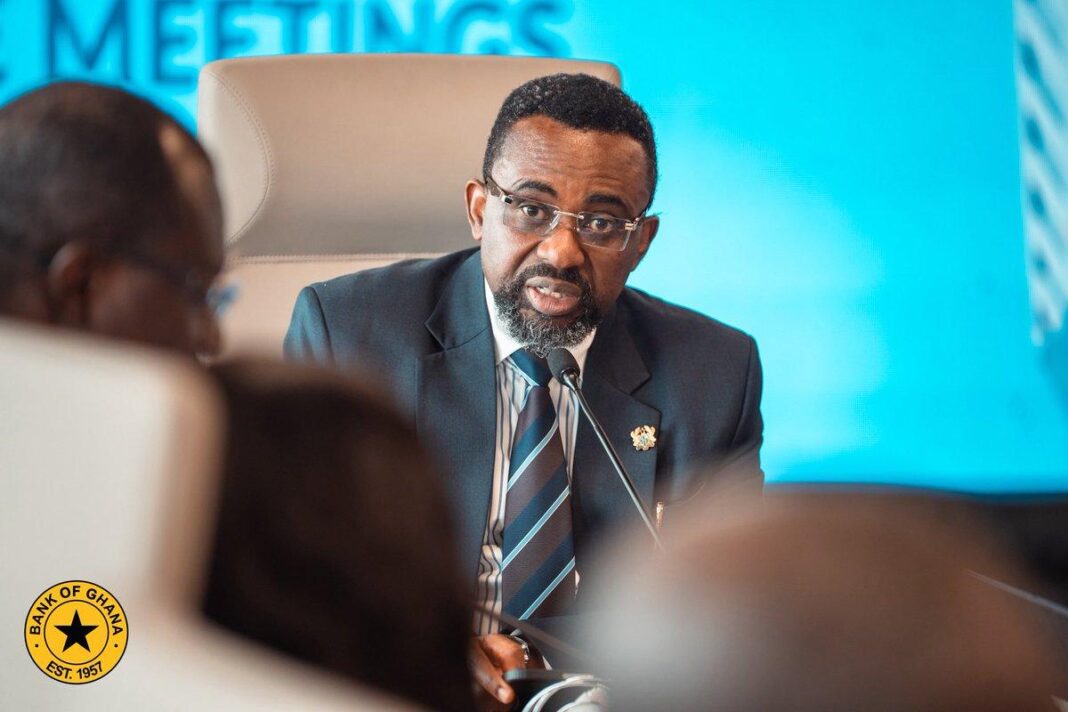

The Bank of Ghana has reduced its Monetary Policy Rate from 14 per cent to 11 per cent, marking a 300 basis point cut as improving economic conditions, stronger private sector lending and declining borrowing costs create room for further monetary easing.
The decision was announced by Bank of Ghana Governor, Dr Johnson Asiama, following the 133rd meeting of the Monetary Policy Committee, which took place from November 16 to 18, 2026.
The latest reduction reflects the central bank’s assessment of sustained improvements in domestic economic activity, easing financial conditions and the anticipated gradual return of inflation towards its medium term target.
Addressing the outcome of the meeting, Dr Asiama indicated that economic growth had remained resilient, with expanding credit to the private sector providing additional support for economic activity. He added that the positive performance was expected to continue through the remainder of the year.
The Governor explained that prevailing market interest rates had already fallen below the previous policy rate of 14 per cent, suggesting that actual monetary conditions in the financial market had become more accommodative than the official benchmark indicated.
He attributed the improved transmission of monetary policy decisions to recent changes in the Bank of Ghana’s monetary operations framework, which have strengthened liquidity management and enhanced the relationship between policy signals and money market interest rates.
As part of efforts to consolidate these improvements, the Monetary Policy Committee has approved further adjustments to the central bank’s monetary operations framework. The measures include replacing the existing open market operations instrument with a seven day instrument and reducing the monetary policy corridor from plus or minus 400 basis points to plus or minus 100 basis points around the policy rate.
The reduction is expected to create additional scope for lower borrowing costs, potentially improving access to financing for businesses and households while supporting investment and private sector expansion.
Recent banking sector statistics indicate a considerable acceleration in private sector credit. Growth in credit extended to private businesses and individuals reached 37.2 per cent in October 2026, compared with 13.9 per cent during the corresponding period in 2025.

Similarly, real private sector credit growth increased to 30 per cent from 5.4 per cent over the same period, suggesting a substantial improvement in lending activity even after accounting for inflation.
The cost of borrowing has also continued to decline, with the average lending rate charged by commercial banks falling to 15.8 per cent in October 2026, compared with 22.2 per cent in October 2025.
Despite these encouraging developments, inflation recorded a marginal increase during October, rising to 5.5 per cent from 5.2 per cent in September. Nevertheless, the inflation rate remained below the lower boundary of the Bank of Ghana’s medium term target.
The central bank expects inflation to gradually return to its targeted range over the medium term, although it has cautioned against several potential threats to the disinflation process.
Among the risks identified are unexpected increases in international crude oil prices, possible disruptions to agricultural production arising from the El Niño weather phenomenon and periodic adjustments in regulated utility tariffs.
Developments in the external sector also featured prominently in the committee’s assessment, with Ghana’s gross international reserves standing at US$12.1 billion as of November 17, 2026.
The reserve position represents approximately 4.4 months of import cover, marking a decline from the US$13.8 billion recorded at the end of December 2025.
The Monetary Policy Committee is expected to reconvene in January 2027 to review prevailing economic conditions and determine the appropriate direction of monetary policy.