
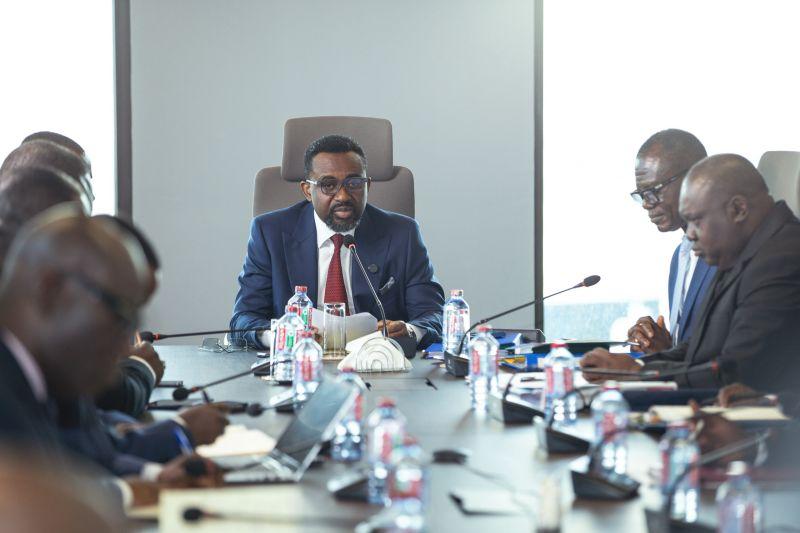

All seven members of the Monetary Policy Committee of the Bank of Ghana have unanimously endorsed the decision to retain the Monetary Policy Rate at 14 percent, citing renewed inflationary pressures and mounting risks from the external environment as key reasons for maintaining the existing monetary policy stance.
The decision was contained in the individual policy submissions presented by members of the Monetary Policy Committee following its 132nd meeting held from September 23 to 24, 2026. The Bank of Ghana subsequently published the submissions, which provide detailed explanations of the considerations that informed the unanimous decision to leave the policy rate unchanged.

A review of the submissions indicates that although members acknowledged the resilience of Ghana’s domestic economy, they remained cautious about the possibility that developments in international markets could generate fresh inflationary pressures and undermine recent gains achieved in stabilising prices.

One member, identified in the decision document as MPC Member 1, observed that the external economic environment had become increasingly challenging, with rising global energy and food prices, heightened geopolitical uncertainty, tighter financial conditions and the possibility of weather related disruptions posing potential threats to Ghana’s inflation outlook.

The member warned that such developments could transmit into the Ghanaian economy through increased import costs, renewed pressure on the exchange rate and additional strains on the external sector.
The member consequently argued that the prevailing circumstances required the central bank to adopt a cautious monetary policy position while allowing sufficient time to determine whether recent inflationary developments would persist and how external shocks could influence the medium term trajectory of inflation.

Another concern highlighted in the submissions was the potential impact of higher energy and transportation costs on domestic prices. Rising petroleum prices, food costs and shipping expenses were identified as factors capable of increasing production and distribution costs across the economy and subsequently placing further pressure on consumer prices.
The Committee therefore considered it prudent to maintain the policy rate at its existing level rather than immediately pursue another adjustment.

According to the members, leaving the rate unchanged would enable the Committee to evaluate the durability of recent inflationary movements and determine whether external disturbances were likely to exert a lasting influence on Ghana’s medium term inflation path.

Inflation Remains a Central Concern for Monetary Policymakers
Inflation featured prominently throughout the individual submissions, particularly concerns surrounding developments in non food inflation.
The Bank of Ghana reported that headline inflation increased from 4.6 percent in July to 5.0 percent in August 2026, with the latest increase largely attributable to developments in non food inflation. At the same time, the central bank indicated that several measures of underlying inflation remained contained, suggesting that the recent increase had not yet translated into a broad based deterioration in underlying price stability.
Members nevertheless remained attentive to the factors capable of generating further increases in domestic prices.
Among the pressures identified were quarterly utility tariff adjustments and rising domestic petroleum prices, both of which have the potential to influence transportation, production, distribution and household expenditure.
Despite these concerns, some members remained confident that inflation could eventually return to the Bank of Ghana’s medium term target of 8 percent, with a tolerance margin of 2 percentage points on either side.
This means the central bank’s target range extends from 6 percent to 10 percent, with 8 percent serving as the midpoint of the medium term objective. The Committee’s assessment therefore suggests that although inflation has recently moved upward, policymakers do not yet consider the development sufficient to warrant an immediate alteration of the current policy rate.
The MPC was also mindful of possible pressure on the Ghanaian cedi arising from heightened uncertainty in international markets.
Greater instability in global financial conditions, higher energy prices and geopolitical tensions could affect capital flows, import costs and foreign exchange demand, potentially placing renewed pressure on the domestic currency.
The members therefore considered maintaining the policy rate at 14 percent as a means of preserving monetary stability while giving the Committee additional time to monitor developments in the domestic and international economies.
Economic Growth Continues to Provide Support
Despite the risks confronting the economy, the MPC recognised several indicators pointing to sustained domestic economic expansion.
Real Gross Domestic Product growth reached 6.0 percent in the second quarter of 2026, while the Composite Index of Economic Activity increased by 14.9 percent year on year in July 2026.
The strong performance of the Composite Index was regarded as evidence that economic activity continued to maintain considerable momentum despite the inflationary and external challenges confronting the economy.
Business and consumer confidence also remained close to historically strong levels, while growth in private sector credit accelerated.
These developments provided further evidence that the Ghanaian economy continued to expand and that the current monetary policy environment was supporting economic activity without, at least for now, generating inflationary pressures that would require an immediate tightening of policy.
The fiscal position also featured positively in the Committee’s assessment.
The primary balance recorded a surplus equivalent to 1.4 percent of Gross Domestic Product, exceeding the fiscal target, while public debt remained broadly stable at approximately 45 percent of Gross Domestic Product.
The MPC regarded these developments as important contributors to macroeconomic stability and as factors capable of strengthening confidence in Ghana’s medium term economic prospects.
The Committee’s assessment therefore presented a mixed picture. On one side, economic growth, fiscal consolidation, improving confidence and relatively contained underlying inflation provided reasons for maintaining the existing monetary policy stance. On the other side, rising inflation, global energy prices, geopolitical uncertainty, exchange rate risks and possible weather related disruptions required policymakers to remain vigilant.
International Reserves Come Under Pressure
The position of Ghana’s international reserves also emerged as an important consideration for the monetary authorities.
The submissions indicated that Ghana’s gross international reserves had declined from approximately US$14 billion to US$12 billion as of September 22, 2026.
The reduction was attributed to substantial payment obligations and rising external debt servicing requirements expected during the period ahead.
The decline in reserves is significant because international reserves provide an important buffer for meeting external obligations and supporting confidence in the country’s ability to manage foreign exchange pressures.
The MPC therefore remained conscious that a combination of elevated external obligations, global uncertainty and possible pressure on the exchange rate could complicate the monetary policy environment.
Nevertheless, the Committee’s assessment was not entirely negative.
The Bank of Ghana continued to point to improvements in Ghana’s broader macroeconomic position, including strong economic activity, fiscal consolidation, stable debt dynamics and improved business and consumer confidence.
The central bank also noted that the underlying inflation environment remained comparatively contained despite the recent increase in headline inflation.
The unanimous decision to retain the Monetary Policy Rate at 14 percent consequently reflects an attempt by the MPC to balance competing economic considerations.
While the Committee did not consider current conditions sufficiently alarming to justify an immediate increase in the policy rate, it also recognised that reducing the rate further could be premature while inflationary risks and external uncertainties remained elevated.
The Bank of Ghana’s own monetary policy framework requires the seven member MPC to assess prevailing economic conditions and the inflation outlook before reaching a decision, with each member casting an individual vote and providing reasons for the preferred policy position.
The latest decision therefore preserves the policy rate at 14 percent, where it has remained since March 2026 after the Committee reduced it by 150 basis points from 15.5 percent. The rate was subsequently maintained at the May, July and September meetings.
The latest position signals that the central bank remains prepared to protect the progress made in reducing inflation while avoiding policy actions that could unnecessarily weaken economic growth.
For households and businesses, the decision means that the central bank is maintaining its present monetary stance while closely observing inflation, exchange rate developments, international reserves, global commodity prices and broader economic activity.
For the MPC, the immediate priority appears to be preserving the gains already achieved in restoring price stability while determining whether the recent increase in inflation represents a temporary development or the beginning of a more persistent upward trend.

